
AfriPolicyCoverCompare. Shortlist. Protect.
Sources & review
Check your countryKenyaLive
Choose your country

Local cover. Local currency. Local policy context.

Live · Published edition. Draft · Pre-release preview, not a live insurance service.

Your choice is remembered on this browser. Changing country does not request a quote or share details with an insurer.

Kenya market Policy context

Insurance information on this edition relates to Kenya. Check the responsible insurer, current policy wording, eligibility and complaint process before choosing cover. Product descriptions are not personalised quotations.

Compare. Shortlist. Protect.

Buildings insurance in Kenya

Compare the cover, price basis and claims information in Kenya. Currency: KES. Confirm the accepted wording and individual quote before choosing.

Buildings insurance comparison

9 supplied product records · 7 distinct provider groups · Received 2026-10-17

Research only: these cover descriptions are not accepted, buyer-specific policies. The sources do not establish current full terms, a matched premium, acceptance of your risk or an active buying route. Buy opens an on-site availability notice only.

Team-supplied product records. Compare the stated cover and conditions; confirm current availability and terms with the responsible insurer.

What these information labels mean
Not yet verified—confirm with insurer.
A detail is missing or has not been established by the current evidence. This does not mean a benefit is excluded.
Not applicable
Use only where the policy evidence establishes that the particular field does not apply. Missing information is not treated as not applicable.
In discussion with the policy provider.
Use only for a named product with a current, record-specific report of actual discussions. Details remain unconfirmed; the label does not establish a partnership or buying route.
Under review
Use only when an actual review is underway. It does not mean the review has been completed or the policy approved.
Quote required
No comparable current payable premium is established here. Ask the insurer for the applicable price, compulsory charges and conditions.
How these descriptions were selected

Owner-approved editorial listings use the team's completed 17 October intake. COMPLETED is an intake status, not contractual verification. Exact product/document references remain internal; company homepages are navigation only.

Provider-group counts are not verified legal-underwriter counts. Team confirmation is retained; no independent contractual review is claimed.

The five source checks are shown separately on each description. They are evidence-status notes, not a product score or recommendation; “unconfirmed” does not mean a benefit is excluded.

Alphabetical by insurer name, with no product score or price ranking.

Choose up to three descriptions. Published prices, rates and periods are shown as stated by their sources, not normalised into a price order.

0 of 3 descriptions selected.

Buildings insurance · Kenya · Compare cover and conditions before price
CompareInsurer and planStarting premiumSupport signalsClarity scoreNext step
01

Britam

Britam Flood Insurance Plan

Flood Property Protection

Adjacent property product; suitability for residential buildings is not confirmed.

Not yet verified—confirm with insurer.

Flood-related insurance; exact covered property and insured events require product documentation

Policy and review details
Entry conditions
Eligibility not established
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
Britam General Insurance Company (K) Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
02

Britam

Fire and Burglary

Property Fire and Burglary

Adjacent property product; suitability for residential buildings is not confirmed.

Not yet verified—confirm with insurer.

Fixed-benefit protection for fire and burglary losses; Claim payment is subject to actual loss; selected benefit limit and applicable excess

Policy and review details
Entry conditions
Individuals protecting homes or businesses; specified business types excluded
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
Britam General Insurance Company (K) Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
10 percent of claim amount; minimum KES 1000 for Option 1 or KES 5000 for Options 2 to 5
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
03

Britam

Home Insurance

Residential Buildings

Not yet verified—confirm with insurer.

Buildings including domestic outbuildings; fixtures; fittings; walls; gates and fences; Fire; earthquakes; storms; lightning; explosions; riots; strikes; malicious damage; overflowing water tanks and pipes; impact by vehicles or animals

Policy and review details
Entry conditions
Owner of a house or flat occupied solely as a private dwelling
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
Britam General Insurance Company (K) Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
04

CIC

Domestic Package

Residential Buildings

Not yet verified—confirm with insurer.

Private residential buildings; outbuildings; fences and swimming pools; Fire; explosion; lightning; burglary; accidental breakage; escape of water; vehicle impact; fire brigade charges; debris removal; alternative accommodation; professional rebuilding fees

Policy and review details
Entry conditions
Homeowners and residential occupiers
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
CIC General Insurance Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
05

First Assurance

Domestic Package

Residential Buildings

Not yet verified—confirm with insurer.

Residential property and household belongings against specified insured risks; Domestic package protection against damage to residential property and contents

Policy and review details
Entry conditions
Residential property owners
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
First Assurance Company Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
06

Heritage

Domestic Package

Residential Buildings

Not yet verified—confirm with insurer.

Residential buildings; household contents; domestic workers and liability protection; Fire; theft; floods; accidental property damage; alternative accommodation; owner and occupier liability

Policy and review details
Entry conditions
Homeowners and tenants; buildings cover applies where the insured has an insurable interest
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
The Heritage Insurance Company Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
07

Madison

Domestic Package

Buildings Section

Not yet verified—confirm with insurer.

Main buildings; outbuildings; fences and gates; Fire; water damage; floods; earthquakes; impact; riots; strikes and malicious damage

Policy and review details
Entry conditions
Residential homeowners
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
Madison General Insurance Kenya Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
08

Mayfair

Domestic Package

Buildings Section A

Not yet verified—confirm with insurer.

Private dwelling; domestic offices; garage; outbuildings; walls; gates; fences and landlord fixtures; Fire; lightning; explosion; riot; strike; earthquake; storm; flood; escape of water; impact; alternative accommodation and loss of rent up to 10 percent of the buildings sum insured

Policy and review details
Entry conditions
Owners of private residential buildings
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
Mayfair Insurance Company Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
KES 500 for each bursting or overflowing water-tank or pipe loss under the published product description
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
09

MUA

Domestic Package

Residential Buildings

Not yet verified—confirm with insurer.

Residential buildings and selected associated domestic risks; Fire; theft; falling trees; earthquakes; natural perils; water escape; road-vehicle impact; alternative accommodation

Policy and review details
Entry conditions
Owners of private residential dwellings
Claim preparation
Contact the insurer/authorised administrator using official homepage; obtain product-specific claims instructions before publication. No deadline assumed.
Legal insurer
MUA Insurance (Kenya) Limited
Waiting period
Not verified — Confirm inception and any property-inspection conditions.

Received by Hagalu / AfriPolicyCover team submission.

Missing information does not establish that a benefit is excluded or not applicable. No provider discussion or completed review is implied by this label.

Submitted availability: Unconfirmed — earlier research identified product; current sale not independently checked. Not independently established.

COMPLETED means data intake processed, not insurer confirmation or public-release approval.

A homepage is navigation only; unsupported contract details remain unconfirmed.

Quote required

Quote Required; KES; insured risk/profile, fees, taxes, payable total and effective dates not confirmed. Do not calculate or advertise a total. Supplied premium note (not a current payable quote): Quote Required

  • Legal identity: unconfirmed
  • Cover scope: unconfirmed
  • Entry conditions: unconfirmed
  • Comparable price basis: unconfirmed
  • Claims route: unconfirmed
Excess, claim and exclusion
Excess
Not verified — obtain applicable excess by section, percentage base and minimum from insurer wording/schedule; do not assume nil.
Important boundary
Research updated 2026-10-17; source homepage is a contact/navigation reference only, not proof of contract terms. Product existence, current availability, underwriter, benefits, exclusions, premium, claims and regulatory status must be independently reconciled before public comparison. No insurer/person confirmation or affiliate agreement claimed. | Import note: homepage is provider navigation only; do not interpret research completeness as contractual approval.

Claims: see Policy and review details.

Not scored

Evidence status only. Not a product rating.

Provider contact is coming soon.

Company homepage ↗
Back to comparison controls

Description comparison

Kenya buying guidance

Kenya / the property decision

Insure the rebuild, not the asking price.

A deed, a mortgage and a home valuation answer different questions. Map the structure you own, the interest you hold and the cost of putting it back before comparing a Kenyan home policy.

Build the value map

Owner-approved editorial edition · no property form, quote or insurer handoff.
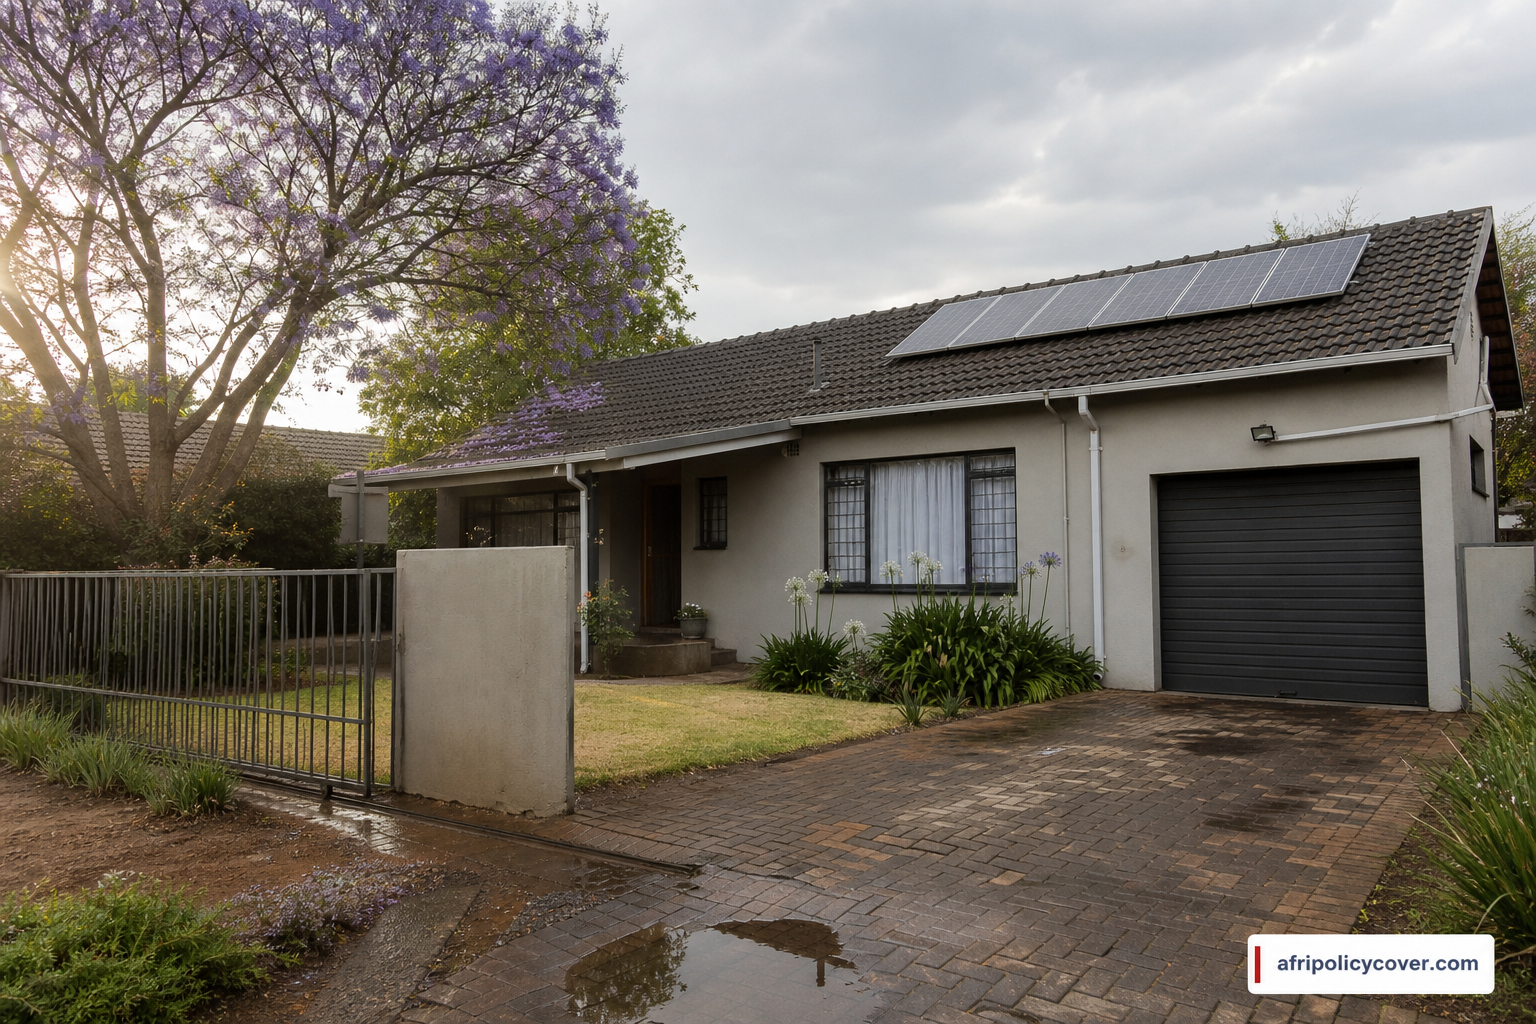
Rain-wet suburban house with a garage, fixed gate and solar panels; South Africa-origin concept art, not a Kenyan insured address
First-party South Africa-origin property image, reused as a concept. It is not a Kenyan address, accepted solar installation, valuation, insurer or claim.
BoundaryDefine what is fixed
InterestIdentify who bears loss
EvidenceKeep the schedule and proof

01 / Begin with the asset

What would it cost to reconstruct this building?

A sale price includes land, location and demand; it is not a reliable reinstatement figure. Commission a current estimate for the actual construction, area, roof, permanent services and site access. Ask the insurer whether boundary walls, gates, tanks, solar equipment and outbuildings fall inside its definition of “buildings” or require separate declarations. A Nairobi apartment owner should check the management company's master insurance for shared roof, lifts, risers and common areas; a private contents policy cannot silently replace that cover.

Illustrative Kenyan rebuild worksheet · invented figures, not a quote or valuation
Cost lineTeaching amountWhat to verify in the wording
Main reconstructionKSh 18,600,000Area, materials, labour, site conditions and reinstatement method.
Demolition and debrisKSh 1,200,000Included in or additional to the building limit?
Professional feesKSh 600,000Architect, engineer, surveyor and approval fees: covered, capped or excluded?
Planning total for building costsKSh 20,400,000Not automatically the sum insured: confirm the insurer's limit structure.
Temporary accommodationKSh 420,000 separatelyOnly if selected, triggered and within the stated time and amount.

The arithmetic: KSh 18.6m + 1.2m + 0.6m = KSh 20.4m of illustrative building-related costs. KSh 420,000 accommodation is a separate hypothetical need, not an insured benefit or amount to add automatically. Land, purchase price and lender balance are not substitutes for a rebuild estimate.

02 / Put names beside the risk

The premium payer and the loss bearer may differ.

The legal insured and any noted lender interest belong on the actual schedule. Tenancy and construction change who controls the building and which contract should answer a loss.

Four different property interests to reconcile with the proposed policy
SituationPrimary questionDocument to obtain
Owner-occupierAre the dwelling, fixed additions and occupancy correctly described?Title, plans, valuation and itemised schedule.
Landlord and tenantDoes the owner insure the structure while tenant contents, rent loss and liability sit elsewhere?Lease, inventory, rental record and owner policy.
Financed homeWhat proof and lender-interest notation does the loan require? A loan balance is not necessarily a rebuild sum.Mortgage conditions, accepted certificate and building schedule.
Build or major renovationAre works, materials, contractors, public liability and partly open structures outside the occupied-home contract?Project contract, permits and construction-risk terms.
Urban apartment

Trace shared fabric

In Nairobi or Mombasa, find the master-policy boundary for the roof, lifts, common pipes, parking and security before valuing only a private unit.

Detached property

List fixed additions

For an Eldoret or Kisumu house, ask specifically about gates, perimeter wall, tanks, solar panels, garages and detached rooms. The picture on this page proves none of these are covered.

Rental or vacant

Declare how it is used

Owner occupation, tenants, short lets and long vacancy can carry different theft, water, inspection and security conditions. Do not borrow another insurer's day count.

03 / First-party Kenya research · checked 10 October 2026

Eleven insurer descriptions; zero accepted comparable policies.

The IRA's 30 March 2026 licensed-entity notice lists these legal insurers with class 03 (Fire Domestic). Their own pages describe domestic or home-cover routes, not eleven accepted, current, like-for-like household contracts. The IRA live insurer route is the purchase-day authority check. A dated class entry is not a property acceptance, quote, premium or claims promise.

Insurer-owned product signals · research only, not a policy ranking
Legal insurer / sourceWhat its page describesStill request in writing
CIC company homepageA domestic package separating buildings, contents, portable property, worker and liability sections.Selected building section and property schedule.
Britam company homepageHomeowner building language alongside a different tenant route.Owner versus tenant eligibility and fixed-property list.
Madison company homepageIndexed insurer page distinguishes homeowners, renters and furnished rental owners; direct local retrieval timed out.Current reachable wording, landlord use and selected perils.
MUA company homepageBuildings and contents, with accommodation discussed for an uninhabitable home.Trigger, accommodation limit and section selection.
GA Kenya company homepageBuildings can include fixed structures and optional allied sections.Boundary structures, occupancy and optional-cover elections.
First Assurance company homepageA current insurer-hosted home-insurance route; public page is not an issued schedule.Full wording, construction, sum and peril definitions.
Mayfair company homepageDetailed domestic sections and product-specific conditions around works, liability and accommodation.Whether this property's works and requested extensions qualify.
Takaful Africa company homepageDomestic-package takaful separates building and other household risks.Participant terms, selected risks and payout basis.
Geminia Insurance company homepageIndexed home-pack description names buildings and fixed additions; direct local retrieval timed out.Current reachable wording and fixed-item limits.
NCBA company homepageOne insurer domestic-package route discusses Flexi and Standard options; not two verified policies.Which option, issuer, limit and excess are actually offered.
ICEA LION company homepageDomestic sections distinguish building, contents, portable property, staff and liability.Selected section A terms and forced-entry, water and liability conditions.

Source integrity and release gap: one other insurer-hosted home page was quarantined because its live footer contained unrelated gambling spam; it is not linked or counted here. Madison and Geminia were indexed on their own domains but timed out on direct local GET. No bank-distributed listing is counted as another insurer. None of these eleven descriptions supplies a complete accepted current policy file, identical-risk KSh price or buyer-specific offer. The insurer register and current wording must be rechecked before any public catalogue.

04 / Test the loss, not the category name

“Buildings cover” does not settle every cause.

Fire and impact

Read the trigger

Ask about fire, explosion, vehicle impact and emergency damage, with the excess and any exclusions beside each peril.

Water and weather

Separate sudden from gradual

Storm, flood, burst pipes, seepage, wear and maintenance may have different treatment. Ask for the flood and escape-of-water wording for the actual address.

Theft and vacancy

Check access conditions

Forced entry, unoccupied periods, locks and security declarations can matter. A policy's theft clause is not proof that an empty home is covered.

Renovation

Declare the works

Alterations can change the risk before the home is habitable. Ask whether contractor all-risks or a project policy is needed; never assume domestic cover extends automatically.

05 / Compare one risk, one date

Make the written offers use the same property brief.

Do not compare a KSh premium unless each issuer has the same address, construction, use, rebuild estimate, fixed additions, selected perils and excess basis. A low price may simply omit a section or use a lower sum.

Like-for-like offer sheet to request from each legal insurer
FieldHold constantWritten evidence to keep
Risk and interestAddress, owner/lender, occupation, tenants and construction type.Proposal answers, interest notation and acceptance.
Rebuild and additionsSame measured estimate, debris, fees and fixed-item declarations.Valuation, section limit and underinsurance clause.
Perils and exclusionsFire, storm, flood, escape of water, theft and renovation status.Selected wording, endorsements, security and vacancy terms.
Cost and serviceSame effective date, insured period, taxes, instalments and excess.Dated KSh quote, legal issuer, claim contact and complaint route.

Price boundary: this page has zero matched KSh premiums. An insurer website, IRA class listing or sample minimum premium is not a quote for this property. Request current accepted written terms before payment; no provider is ranked here.

06 / After damage

Keep the loss legible before repairs erase it.

  1. 01

    Secure people and the site

    Use emergency services when needed, stop further loss only where safe and keep receipts for urgent mitigation.

  2. 02

    Notify the verified issuer

    Record the date, policy number, incident description, claim reference and any adjuster's preservation instructions.

  3. 03

    Document the cause and extent

    Take safe dated photographs of roof, walls, services, water path, entry points and damaged fixed items. Obtain any relevant police or fire record.

  4. 04

    Prove cost and interest

    Retain title or lease, lender note, plans, earlier valuation, repair estimates, invoices and contractor correspondence.

  5. 05

    Request the written decision

    Reconcile the accepted peril, limit, underinsurance, excess and exclusions. Ask the insurer for a written response before using the IRA complaint route.

Questions before signing

Buildings insurance in Kenya: what still needs an answer?

Is the building value the purchase price?

Not necessarily. Market price includes land and location. Ask for a current reconstruction estimate and confirm whether the insurer uses reinstatement, declared value or another basis.

Should the sum include land?

Do not assume so. Land ordinarily remains after building damage; ask the insurer to define the insured building and how debris, fees and fixed services are limited.

Are solar panels, gates and water tanks covered?

Only the selected wording and schedule can answer. List each fixed addition, its value and installation before seeking acceptance.

Can a tenant insure the landlord's structure?

A tenant should read the lease and insure the financial interest they hold. Contents and tenant liability may be relevant, while the owner's structure and any lender interest need separate confirmation.

Does a bank's home-insurance page name my underwriter?

Not always. A bank may distribute another insurer's policy. Verify the legal issuer, current IRA status and actual accepted schedule.

Does a home policy cover construction or major renovation?

Do not assume it does. Declare works, materials, contractor responsibility, open structures and intended occupation. Ask whether project or contractors all-risks cover is required.

Does every Kenyan policy cover floods?

No country-wide flood promise follows from a domestic-package label. Check the property's location, selected event, exclusions, excess and any water-damage conditions.

What if my home is left vacant?

Tell the issuer why and for how long it will be unoccupied. Security, inspections, theft and water clauses are policy-specific; do not assume another insurer's vacancy period applies.

Will accommodation or lost rent be paid after damage?

Only if the written contract includes the relevant extension and insured event, with the right limit and time period. Owner accommodation and landlord rent are different interests.

What if my rebuild estimate is too low?

Ask how the particular wording handles underinsurance and partial loss. Keep a current estimate and recheck it after extensions, material-cost changes or new fixed equipment.

Which Kenyan buildings insurer is cheapest?

There is no defensible ranking here. Eleven insurer-owned descriptions are research signals, not complete accepted comparable policies; this page has no matched current KSh quotes.

Where do I challenge a buildings claim decision?

Ask the legal insurer for its written reason and complaint process, preserving the schedule, evidence and correspondence. Check the current IRA complaint route if the dispute remains unresolved.